KYC & Customer Risk Profiling

Know your customer on day one, and every day after.

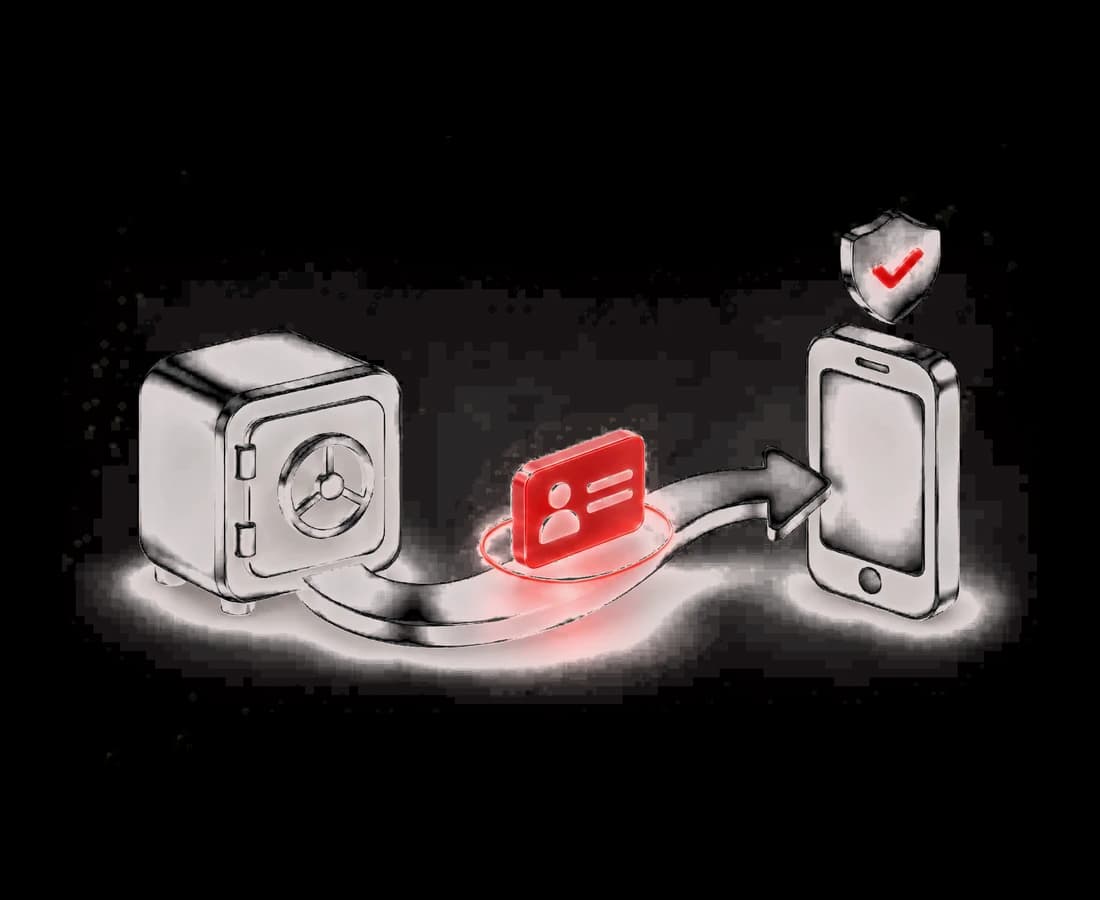
Digital identity checks at onboarding, then a customer risk score that keeps updating as the customer's life and activity change, synced straight back to your core banking system.

For compliance, onboarding and KYC teams in banks, SACCOs, microfinance and fintechs

eKYC & biometricsDynamic risk scoringCore banking sync
Trusted by banks and financial institutions
  • KCB
  • NCBA
  • Co-op Bank
  • DTB
  • HFCB
  • DIB
  • IPSL
20+
years in enterprise technology
95%
projects on time

KYC done once, then forgottenFrom a one-off check to risk known for life.

Today
  • Branch visits and photocopied IDs
  • A risk rating set at account opening
  • Reviews driven by the calendar
  • KYC data that differs by system
With FinSense
  • ID, face and liveness checked digitally
  • A rating that updates with activity
  • Reviews triggered by real change
  • One current record in every system

Slow at the door, blind after it.

Manual ID checks

Photocopies and branch visits slow every account opening, and fakes still get through.

Ratings that go stale

A risk rating set once at onboarding misses how the customer's activity changes.

Records that disagree

KYC data and risk ratings sit in separate systems, so teams work from different versions.

What it does

A glass phone and ID card, with a red liveness ring around the selfie
How we work
  1. Read ID documents automatically on the customer's phone
  2. Match the face to the document with a liveness check
  3. Check against national ID registries
01

Digital Identity Verification

Real customers in, stolen and synthetic identities out.

The challenge

Manual ID checks slow every account opening, and photocopies are easy to fake.

What you receive
  • Document capture with automatic data extraction
  • Face match and liveness detection
  • Checks against the identity sources you use
The outcome

Customers verified in minutes, without a branch visit.
A glass risk gauge with its needle in the red
How we work
  1. Agree your risk factors and weights
  2. Score every customer from profile and activity
  3. Rescore automatically when something changes
02

Dynamic Customer Risk Scoring

A risk rating that moves when the customer does.

The challenge

A rating set at onboarding goes stale, so higher-risk customers are reviewed too late.

What you receive
  • A configurable risk model
  • Automatic rescoring and review triggers
  • Enhanced due diligence workflows
The outcome

Reviews that follow real risk, not the calendar.

One verified glass KYC record shared out to several systems
How we work
  1. Connect your core and channel systems
  2. Push verified data and ratings as they change
  3. Keep an audit trail of every update
03

Core Banking Sync

One customer truth across every system.

The challenge

KYC data and risk ratings live in separate systems that rarely agree.

What you receive
  • Two-way sync with your core
  • Ratings shared with AML and screening
  • A full history of every change
The outcome

Every team works from the same, current customer record.

AI

AI that reads the ID and knows the face is real.

Computer vision checks documents and faces at onboarding, and models keep each customer's risk rating current.

  • Reading the ID documentWhat AI does: Text and photo extracted automatically
  • Is this the same person?What AI does: Face match between the selfie and the ID
  • Is the person really there?What AI does: Liveness detection stops photos, masks and deepfakes
  • Has the customer's risk changed?What AI does: Activity and profile shifts trigger a new score

One platform. Seven modules.

Each module stands alone. Start with the one that is most urgent, then add the rest on the same platform, sharing one customer view and one audit trail.

One customer record, everywhere.

Verified identity and the live risk rating flow back to every system that needs them.

Connects to

  • Temenos T24 / Transact
  • Oracle FLEXCUBE
  • Infosys Finacle
  • Finastra
  • Your own core
  • National ID registries
  • AML and screening
  • Onboarding channels

Runs where you need it

  • On-premise, in your data centre
  • Private cloud
  • Secure public cloud

Built around

  • CBK KYC and customer due diligence rules
  • Kenya Data Protection Act consent
  • Enhanced due diligence for high-risk customers
  • A history of every rating change

Your risk model first, then the journey.

FinSense configures the platform to your rules, connects it to your systems, trains your team and supports it locally.

  1. Assess

    Your KYC rules, risk model and onboarding today.

  2. Configure

    Checks, risk factors and review triggers.

  3. Integrate

    Identity sources, your core and channels.

  4. Launch

    Live on one product, then extended.

Questions about KYC & Customer Risk Profiling

How is this different from Digital Onboarding?

Digital Onboarding is the whole customer journey to an active account. This module is the compliance core inside it: identity checks and a risk rating that keeps updating for the life of the customer.

Can we use our own risk model?

Yes. Your risk factors and weights are configured into the model, and changes are versioned so you can show the regulator which model rated whom.

Do we have to buy the whole financial crime suite?

No. Each module stands alone. Start with the one your regulator or your losses make urgent, and add others later on the same platform, sharing one customer view and one audit trail.

Verify faster. Know your customers longer.

See digital KYC and dynamic risk scoring on journeys like yours.